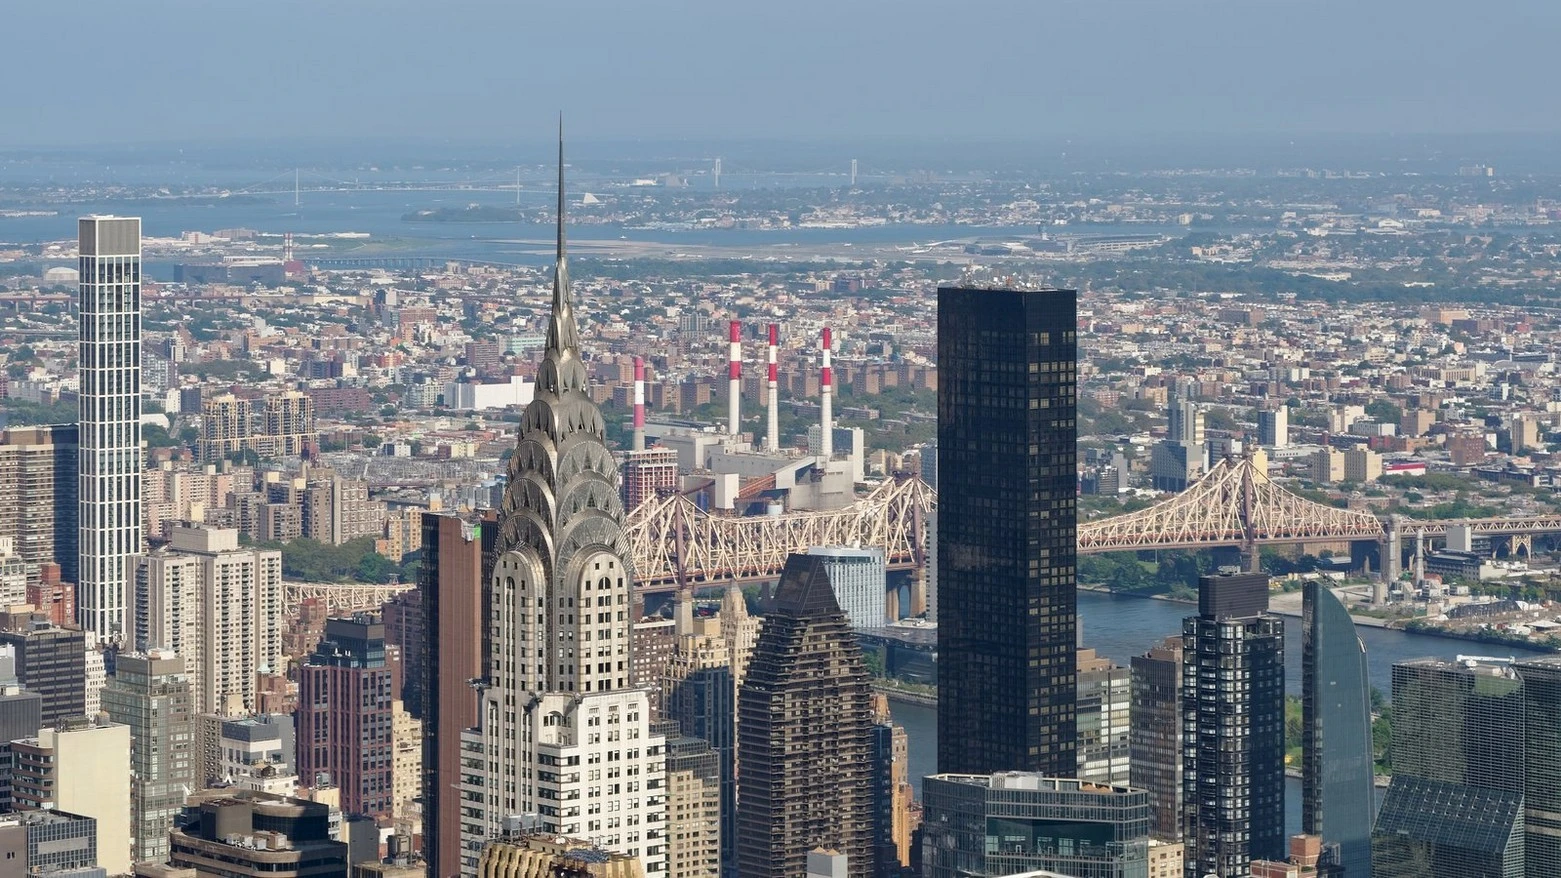
Two years ago the Chrysler Building was a cautionary tale: unpaid rent, an insolvent co-owner, eviction proceedings and tenants complaining about cracked ceilings. This fall it became something else entirely, the first acquisition of a brand-new vehicle built to buy U.S. office buildings. That shift tells us a lot about where smart money thinks the office cycle is heading.
What happened
In early October, Tishman Speyer signed a 150-year ground lease with Cooper Union, the private college that owns the land under the 77-story tower at 405 Lexington Avenue. According to Bisnow, Tishman agreed to pay $235 million plus future ground rent, backed by a group of institutional investors led by Canada's Public Sector Pension Investment Board. It plans to reposition the 1.3 million-square-foot landmark as a boutique office tower and is using 100% equity to do it.
On Oct. 23, the deal took on a second life. Dutch pension investor Bouwinvest Real Estate Investors and Tishman Speyer announced a separately managed account to buy office assets across the United States, and the Chrysler ground lease is its first investment. The account will target well-located buildings that need renovation or repositioning, in gateway cities like New York, Boston, Chicago and San Francisco as well as fast-growing markets. It sits alongside a Tishman Speyer office club with about $700 million of equity ready to deploy, which the companies said could fund roughly $1.5 billion of acquisitions once debt is added.
From $800 million to a fresh start
The building's recent history is a crash course in office-cycle risk. The Abu Dhabi Investment Council paid $800 million for a 90% stake in 2008. RFR and Austria's Signa Holding bought the tower in 2019 for just over $150 million, Bisnow reported, a price weighed down by ground rent that was set to climb from $7.8 million in 2018 to as much as $32.5 million.
Signa filed for insolvency in November 2023. Rent went unpaid, renovations stalled, and Cooper Union began eviction proceedings in September 2024. A judge sided with the school in January 2025, and Cushman & Wakefield has managed the building since. Now Tishman Speyer, which once held the ground lease before selling out to RFR, is back in control.
The business plan
Roughly half the building is vacant, according to Savills Vice Chairman David Heller, who represented Cooper Union. The plan is to turn 75% of the vacant or soon-to-be-vacant space into prebuilt office suites, convert the 61st floor into an amenity clubhouse with an outdoor terrace and food and beverage, and refresh the art deco exterior, including the famous crown. Heller said there was a tremendous amount of interest in the lease, noting there is only one Chrysler Building.
Bouwinvest's director of North American investments, Robert Wagenaar, called the tower a fitting first investment and said the firm sees a tactical opportunity in U.S. office with a brown-to-green angle, meaning older buildings upgraded to modern, efficient standards.
Why now: Manhattan's flight to quality
The bet rests on a tight market at the top. Bisnow, citing Colliers, reported that Manhattan is on pace for its most office leases signed since 2000, with virtually no availability left in the best towers, while millions of square feet of older space have been pulled off the market for residential conversion. The Grand Central submarket, home to the Chrysler Building, posted the highest direct asking rents in Manhattan in the third quarter at $113.45 per square foot, according to Avison Young.
What it means for CRE investors and owners
For investors, the takeaway is that foreign pension capital is coming back to U.S. office, but selectively. The target is not any office building. It is a well-located asset with a fixable problem, bought at a reset basis and upgraded into the top tier of its market.
For owners of older Class B buildings near transit, the message is mixed. Buyers are willing to fund repositioning plans, but they want a clear path to trophy-level rents. Prebuilt suites, real amenities and energy upgrades are becoming the price of admission, not extras.
For owners of ground-leased properties, the Chrysler saga is a reminder to stress-test escalating ground rent. Rising ground payments were the main reason the building's value deteriorated. Any buyer or lender will look hard at that structure, and so should you.
And for the market overall, capital raised specifically for office is a sign the bottom may be behind us in prime submarkets. The money is starting to pick its spots.
Sources
Bisnow, "Tishman Speyer Retakes Chrysler Building, Plans $235M Renovation" (Oct. 7, 2026)
Published by The Basis. Research dates, source references and illustrative assumptions are retained from the original article.