Thursday, November 5, 2026Commercial real estate news
About The Basis
the basis.

Commercial real estate.
The full picture.

Saved storiesLatest stories
Rates
RATE WATCHDaily benchmarks10-year Treasury4.84%-6 bpAs of Nov 55-year Treasury4.59%-10 bpAs of Nov 5SOFR3.92%-2 bpAs of Nov 5Effective Fed funds3.88%UnchangedAs of Nov 5
STATE MARKET PULSESeptember 2026 · BLS · Monthly
New YorkJobs YoY +0.2%Unemployment 4.3%FloridaJobs YoY +0.6%Unemployment 4.4%TexasJobs YoY +1.1%Unemployment 4.4%CaliforniaJobs YoY +0.7%Unemployment 5.1%New JerseyJobs YoY +0.1%Unemployment 4.2%North CarolinaJobs YoY +1.3%Unemployment 3.4%AlabamaJobs YoY +1.0%Unemployment 3.5%AlaskaJobs YoY +1.2%Unemployment 4.3%ArizonaJobs YoY +0.6%Unemployment 4.9%ArkansasJobs YoY +0.9%Unemployment 3.9%ColoradoJobs YoY +0.4%Unemployment 4.1%ConnecticutJobs YoY +0.9%Unemployment 5.1%DelawareJobs YoY +0.3%Unemployment 4.6%District of ColumbiaJobs YoY -3.5%Unemployment 5.6%GeorgiaJobs YoY 0.0%Unemployment 3.3%HawaiiJobs YoY +0.1%Unemployment 2.8%IdahoJobs YoY +1.0%Unemployment 3.6%IllinoisJobs YoY +0.2%Unemployment 4.6%IndianaJobs YoY -0.4%Unemployment 3.4%IowaJobs YoY +0.3%Unemployment 3.2%KansasJobs YoY +0.3%Unemployment 3.8%KentuckyJobs YoY 0.0%Unemployment 4.7%LouisianaJobs YoY +1.8%Unemployment 4.0%MaineJobs YoY +0.1%Unemployment 3.3%MarylandJobs YoY -0.5%Unemployment 3.9%MassachusettsJobs YoY +0.4%Unemployment 4.3%MichiganJobs YoY 0.0%Unemployment 5.0%MinnesotaJobs YoY +1.2%Unemployment 4.5%MississippiJobs YoY +0.6%Unemployment 3.3%MissouriJobs YoY +1.0%Unemployment 3.6%MontanaJobs YoY -1.0%Unemployment 3.1%NebraskaJobs YoY +0.4%Unemployment 2.9%NevadaJobs YoY +1.6%Unemployment 4.7%New HampshireJobs YoY +0.3%Unemployment 2.6%New MexicoJobs YoY +1.3%Unemployment 4.7%North DakotaJobs YoY +0.2%Unemployment 2.2%OhioJobs YoY +0.3%Unemployment 3.4%OklahomaJobs YoY +0.8%Unemployment 4.2%OregonJobs YoY -0.1%Unemployment 5.0%PennsylvaniaJobs YoY +0.7%Unemployment 3.6%Rhode IslandJobs YoY -0.1%Unemployment 3.6%South CarolinaJobs YoY +2.3%Unemployment 4.0%South DakotaJobs YoY +0.4%Unemployment 2.0%TennesseeJobs YoY +0.8%Unemployment 3.4%UtahJobs YoY +1.5%Unemployment 3.5%VermontJobs YoY -0.1%Unemployment 2.6%VirginiaJobs YoY -0.6%Unemployment 3.6%WashingtonJobs YoY +0.7%Unemployment 4.8%West VirginiaJobs YoY 0.0%Unemployment 4.0%WisconsinJobs YoY +0.4%Unemployment 3.2%WyomingJobs YoY +0.9%Unemployment 3.0%
All states
Distress & CMBS / NEWS

San Francisco foreclosure tax measure takes commanding lead

A proposed change to San Francisco’s foreclosure transfer-tax exemption leads in preliminary returns, with implications for lenders and distressed-asset investors.

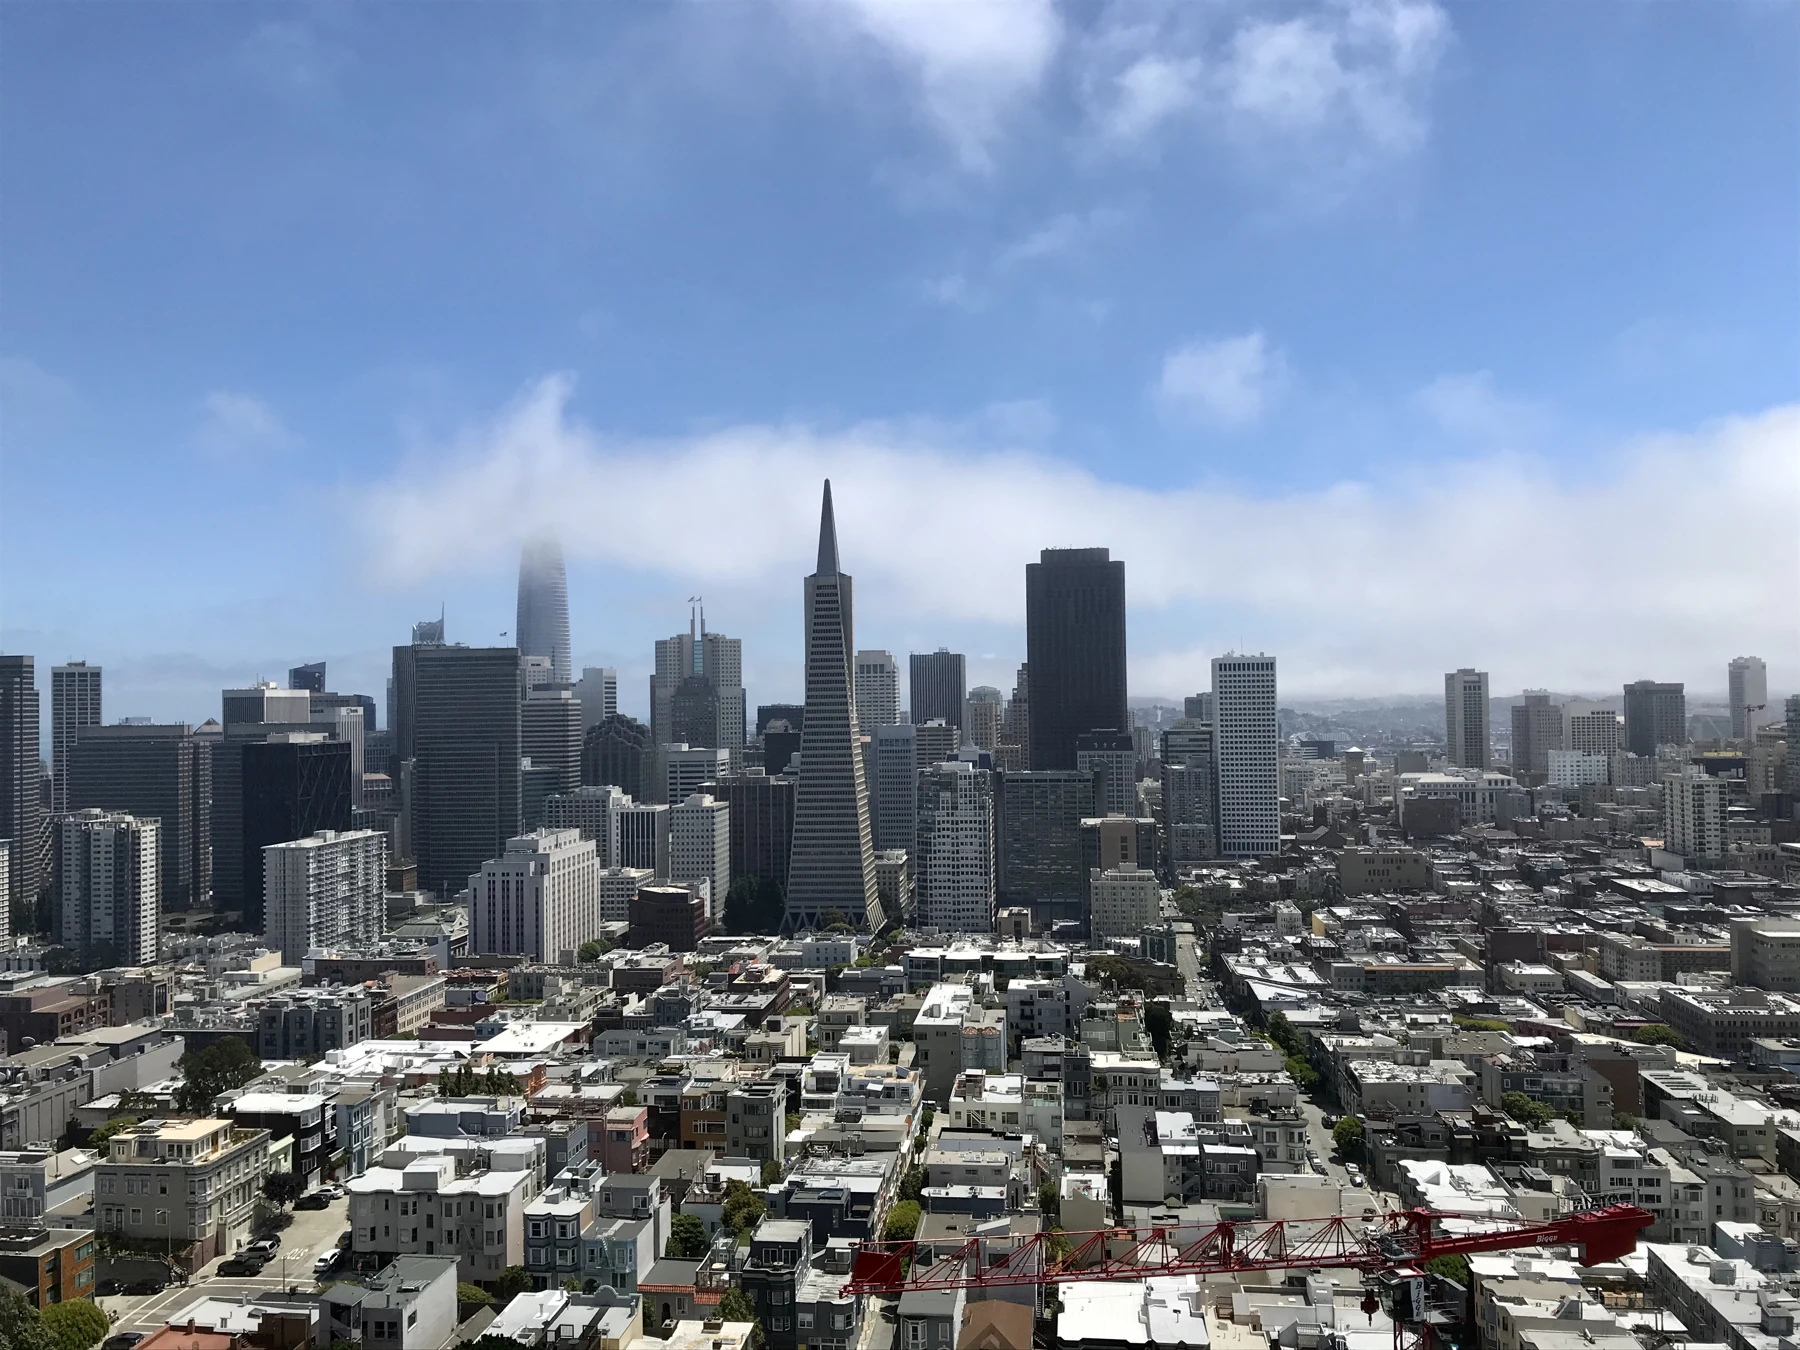
Downtown San Francisco viewed from Coit Tower. Archival photo, July 14, 2019.
Downtown San Francisco viewed from Coit Tower. Archival photo, July 14, 2019. Photo: GyozaDumpling / Wikimedia Commons · CC BY-SA 4.0. Resized, converted to WebP and cropped to fit the layout. Adapted image remains under CC BY-SA 4.0.

San Francisco’s Proposition J held a commanding lead in preliminary election returns Wednesday, putting lenders and distressed-property investors on notice of a potential new tax cost when buildings change hands through foreclosure.

KQED’s results page showed approximately 79% support, with 135,129 yes votes and 35,793 no votes in its November 3, 11:53 p.m. Pacific update. The measure requires a simple majority. The count remained unofficial.

Proposition J removes a transfer-tax exemption for specified transfers of property to lenders through foreclosure or to avoid foreclosure. The city’s official ballot description identifies commercial, industrial and large residential properties and tax rates ranging from 0.5% to 6% of fair market value.

The underlying legislation sets March 1, 2027, as the start date for the exemption change. Residential and mixed-use properties with fewer than five residential units would remain outside the change, according to the legislation’s summary.

For the CRE industry, that makes the proposal a transaction-cost story with immediate relevance to distressed-asset analysis. A lender evaluating whether to take title would need to account for a transfer-tax liability that previously could have been exempt. Investors reviewing troubled debt would likewise need to understand how a potential title transfer fits within the new rules.

The result does not establish that lenders will avoid foreclosures or that borrowers will receive more generous workouts. Those decisions depend on the economics and legal terms of each loan. What changes is one component of the calculation.

The city’s ballot description estimates annual revenue of $100 million to $150 million. That is an estimate tied to future taxable activity, not money already collected. The scale of the forecast also underscores why the measure matters to owners of high-value assets: a percentage-based transfer tax can become a substantial expense when applied to a large property.

The exception for smaller residential and mixed-use buildings is another reason to avoid treating the vote as a universal tax on every foreclosure. Property classification, unit count, transaction structure and timing will determine whether a particular transfer falls within the measure.

Until the election is certified, the immediate conclusion is that Proposition J is strongly ahead. For lenders and investors with affected San Francisco exposure, the next practical step is to evaluate transactions expected to close on or after the proposed March effective date.

Sources

KQED San Francisco election results

Official Proposition J ballot description

San Francisco legislation file 260692

Published by The Basis. Research dates, source references and illustrative assumptions are retained from the original article.